
How to read a card processing statement
This is a real September statement from a small service business, broken down line by line. The business name, owner, address and account number are removed. Every number is real.
Start with one number
Ignore the rate you were quoted. Divide what you paid in fees by what you sold on cards. That’s your effective rate, and it’s the only fair way to compare two processors.
Where the $165.92 went
Every fee on a statement goes to one of three places. Only one of them is up to your processor.
Paid to the bank that issued your customer’s card, like Chase or Capital One. Visa and Mastercard set these rates, and every processor pays the same ones.
Same with any processorAssessments and small network fees for using the Visa and Mastercard networks. Also the same everywhere.
Same with any processorThe processor’s markup plus its monthly fees. This is the part you can shop around and negotiate.
The part you can changeInterchange, card by card
Nine sales landed in five interchange categories. Each one has its own rate: a percentage of the sale plus 10¢. The card your customer uses and how you take it decide which category applies.
| Card and category | How it was taken | Sales | Rate | Interchange | Effective |
|---|---|---|---|---|---|
| Mastercard World EliteMC-WORLD ELITE MERIT III | In person | $1,800.00 · 3 | 2.30% + $0.10 | $41.70 | 2.32% |
| Visa Signature Preferred, servicesVI-SERVICES SIGN PREFERRED | Services rate | $1,350.00 · 3 | 2.30% + $0.10 | $31.35 | 2.32% |
| Mastercard EnhancedMC-ENHANCED MERIT I | Keyed in | $1,200.00 · 1 | 2.10% + $0.10 | $25.30 | 2.11% |
| Mastercard High ValueMC-HIGH VAL MERIT I | Keyed in | $250.00 · 1 | 2.60% + $0.10 | $6.60 | 2.64% |
| Mastercard High ValueMC-HIGH VAL MERIT III BASE | In person | $175.00 · 1 | 2.30% + $0.10 | $4.13 | 2.36% |
| Total | $4,775.00 · 9 | $109.08 | 2.28% |
“World Elite”, “High Value” and “Signature Preferred” are premium rewards cards. The issuing bank funds those rewards partly through higher interchange.
The same High Value Mastercard cost 2.30% in person and 2.60% when keyed in. “Merit III” means the card was present; “Merit I” means it was typed in.
With an average sale of $530, the 10¢ per transaction barely moves the rate. On a $10 sale the same 10¢ adds a full 1%.
Card network fees: $9.43
Visa and Mastercard charge a small percentage on every dollar, plus tiny per-transaction fees with long names. They’re real, but they’re small and the same at every processor.
- Mastercard assessment0.14% of $3,425.00$4.80
- Visa network feeMonthly, card present$2.00
- Visa assessment0.14% of $1,350.00$1.89
- Mastercard large ticket assessmentOn sales of $1,000 or more$0.23
- Nine per-transaction network feesAuthorization, clearing, address and security code checks, licensing$0.51
- Total$9.43
The processor’s share: $47.41
This statement uses interchange plus pricing: card costs are passed through at cost, with a stated markup on top. That makes the processor’s share easy to find.
- Markup (“sales discount”)0.50% of all card sales$23.88
- Platform access monthly feeFixed, every month$20.00
- Regulatory product feeFixed. Despite the name, it’s set by the processor, not the card brands.$3.50
- Address verification fee2 keyed transactions$0.03
- Total$47.41
The $23.50 in fixed monthly fees was 0.49% of September’s sales. In March, when this business ran $825 in cards, the same $23.50 would have been 2.85% on its own.
Why your bank deposits don’t match
Each sale is deposited in full. The month’s fees come out in one lump after the month ends. So September’s deposits paid for August’s fees, and September’s $165.92 comes out in early October.
Here’s where each number lives
The first three pages of the statement, with the business and account details removed. Tap a page to see it full size.
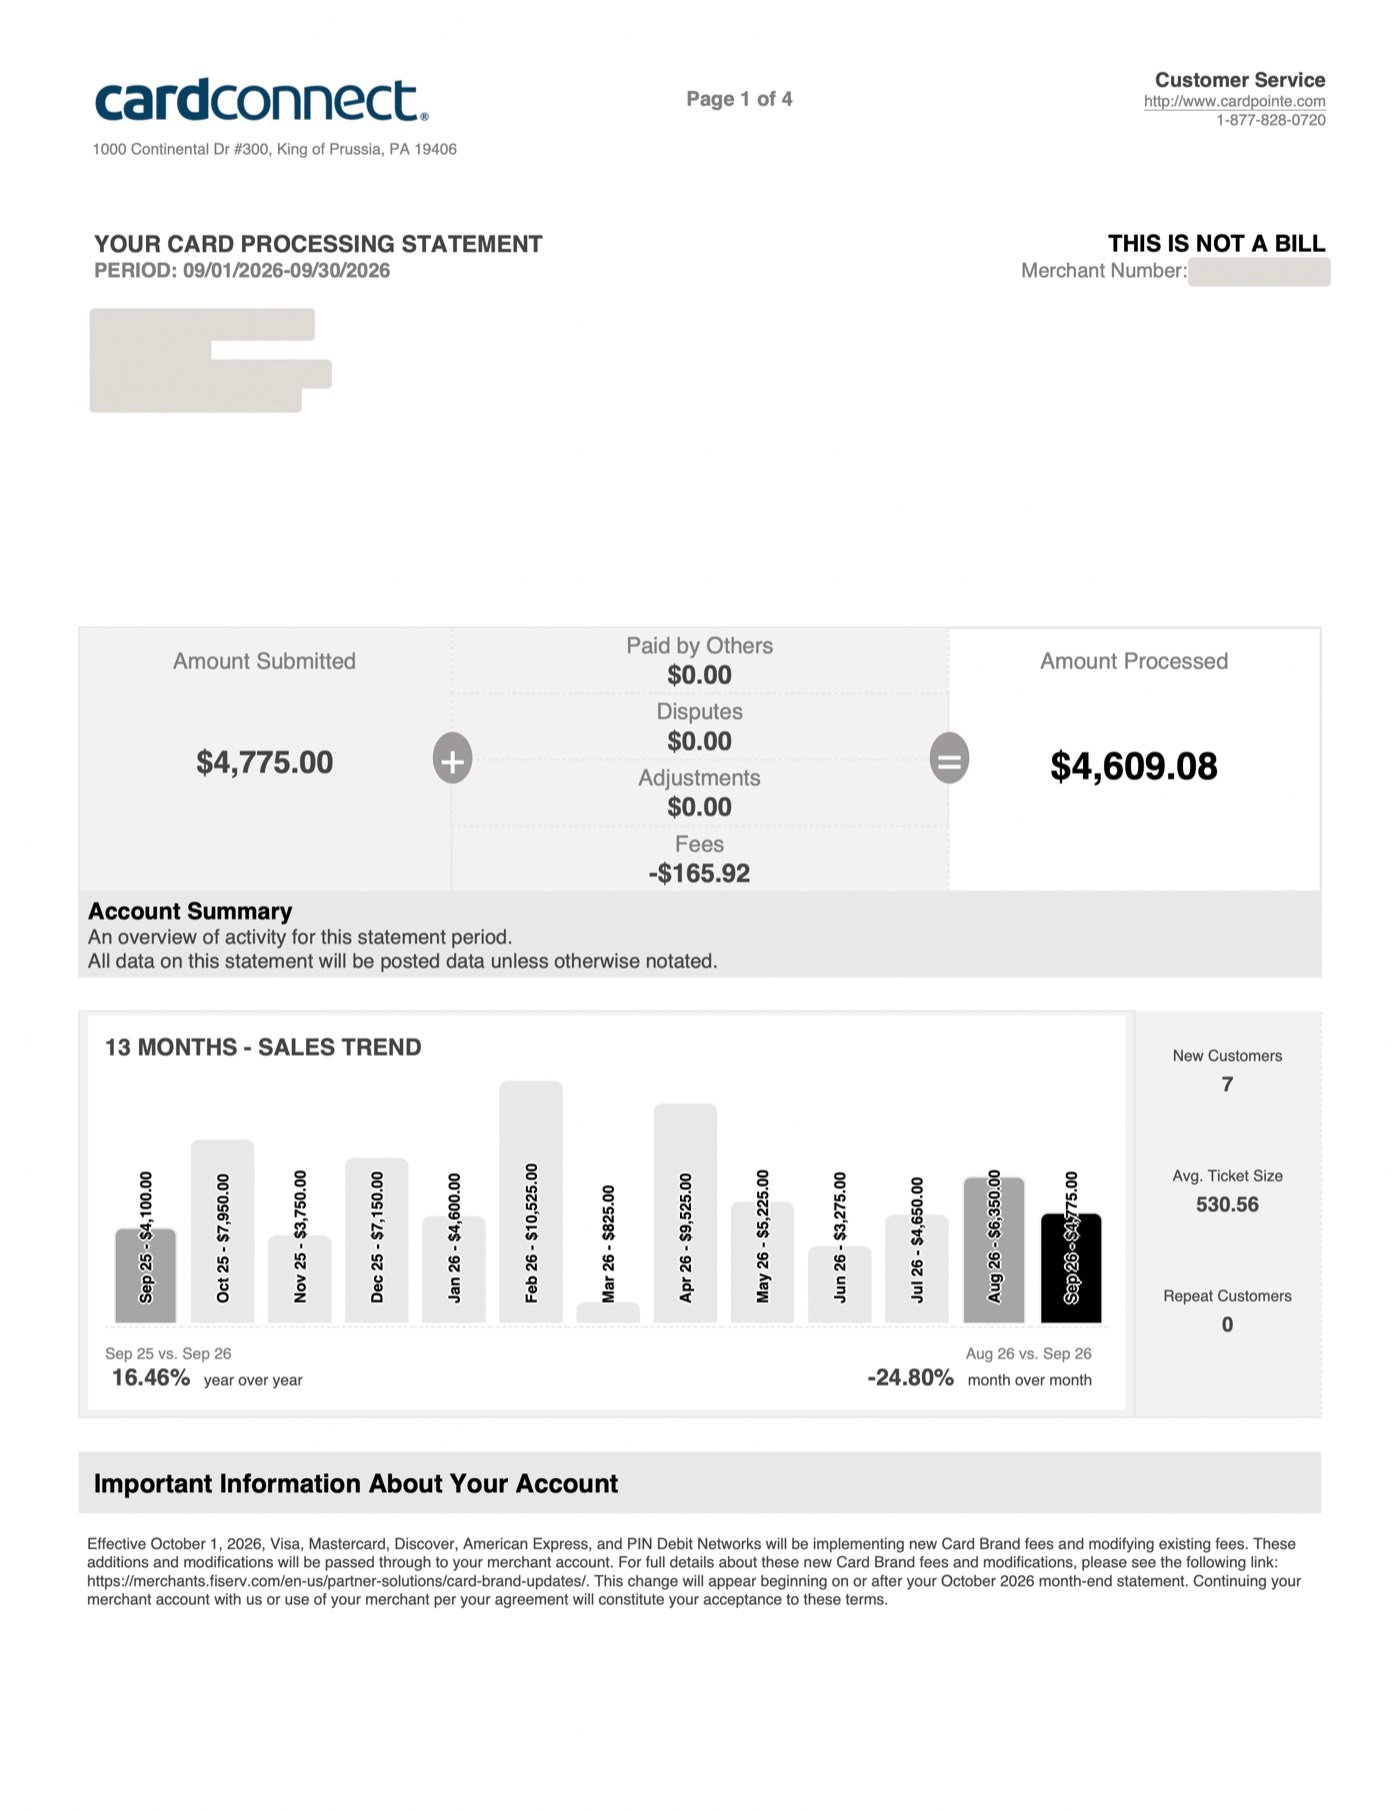 Page 1: Account summaryCard sales, total fees and a 13 month trend. Step 1 uses the top box.
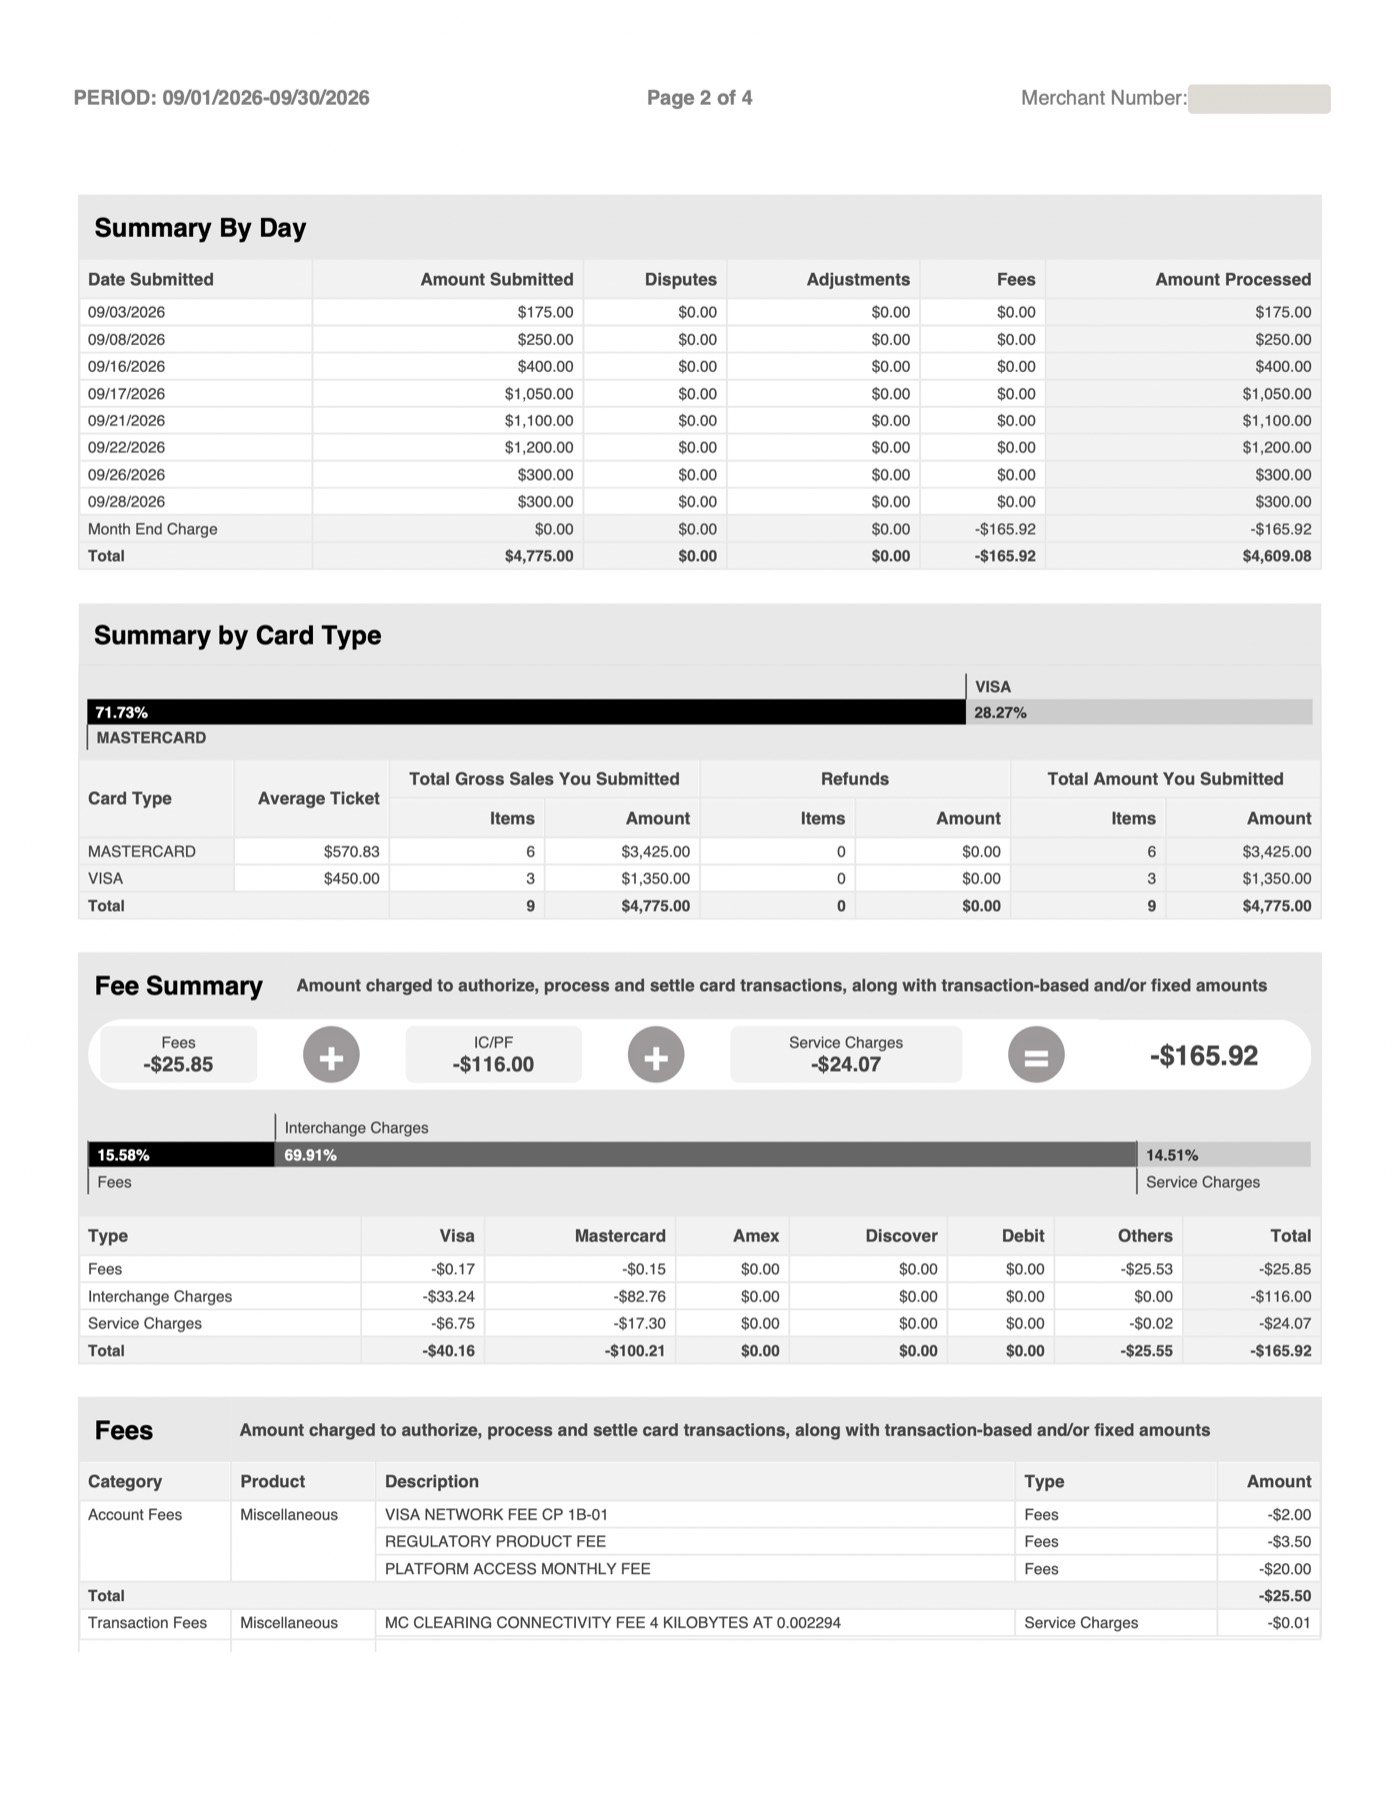 Page 2: Fee summarySales by card brand, the fee totals and the fixed monthly fees from Step 5.
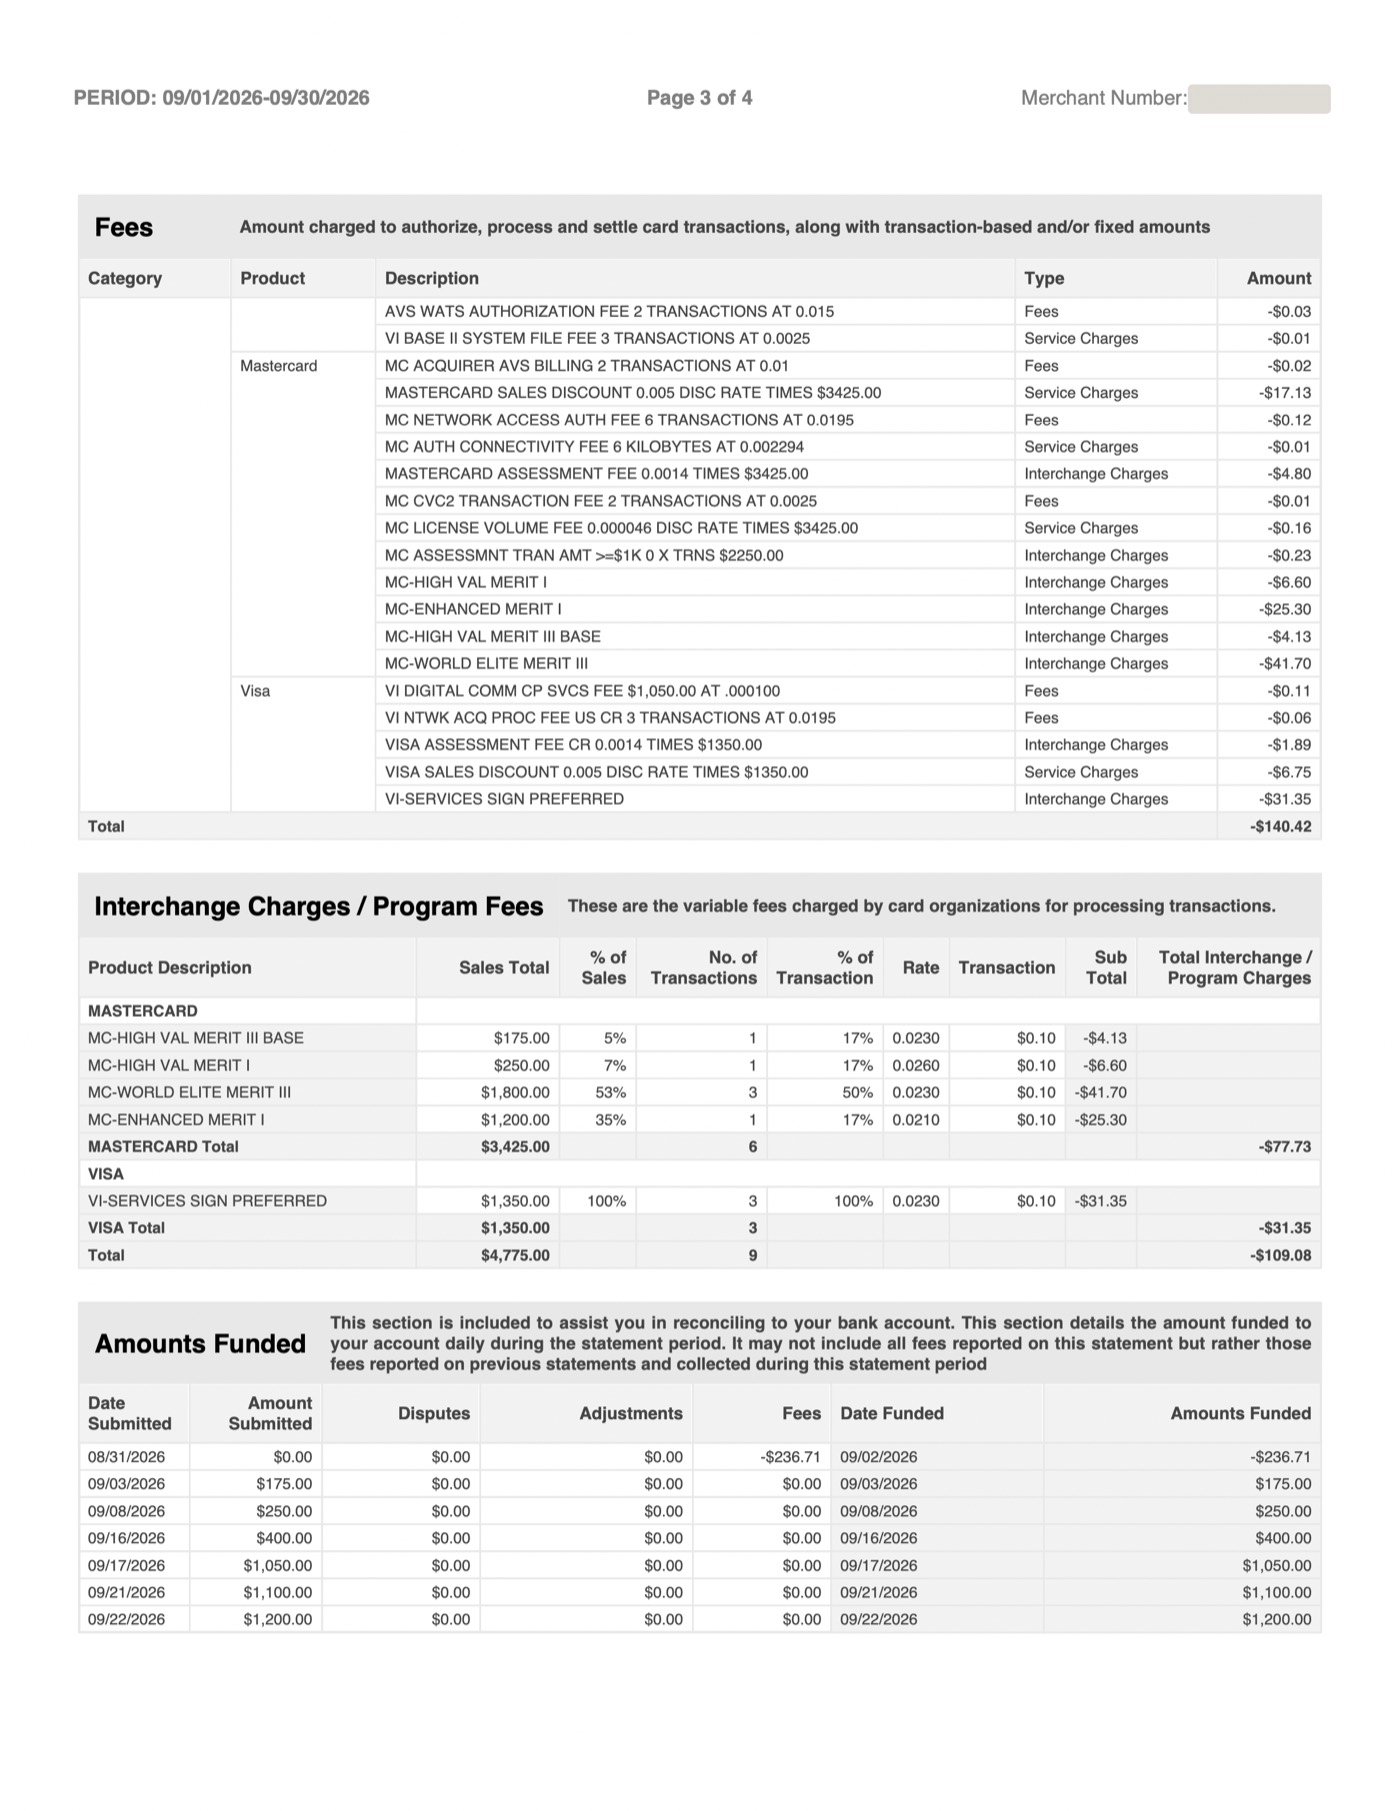 Page 3: Interchange and fundingEvery fee line, the interchange table from Step 3 and the daily deposits from Step 6.
Check your own statement in five minutes
- Find your effective rate. Total fees divided by total card sales. Anything well above 3% for an in-person business is worth a second look.
- Find the interchange table. If your statement has one, you’re on interchange plus pricing. If it only shows “qualified” and “non-qualified” rates, the card costs are bundled and harder to check.
- Find the markup. Look for a percentage labeled discount, markup or basis points, plus any per-transaction fee your processor adds.
- Add up the fixed monthly fees. Platform, statement, PCI, regulatory and minimum fees. They hurt most in slow months.
- Read the notices. This statement warned about new card brand fees starting in October, in a paragraph on page 1.
Rates shown are from this September 2026 statement. Visa and Mastercard update interchange rates, usually twice a year, and the categories you see depend on your business type and how you take cards.
Want yours broken down like this?
Send us one statement. We’ll find your effective rate, show you which fees you can change, and tell you plainly if switching is worth it.